
The Bull Case For CrowdStrike (CRWD) Could Change Following Falcon’s Launch In The OpenAI Marketplace
In late September 2026, CrowdStrike announced that its Falcon platform became available in the OpenAI Marketplace, allowing eligible OpenAI enterprise customers to allocate part of their existing OpenAI commitments toward purchasing CrowdStrike's AI-powered cybersecurity services.
This move not only broadens distribution for Falcon but also ties CrowdStrike more closely into enterprise AI spending as companies secure emerging AI agents.
Next, we'll examine how Falcon's new availability through the OpenAI Marketplace could influence CrowdStrike's AI-focused investment narrative and growth expectations.
This technology could replace computers: discover 25 stocks that are working to make quantum computing a reality.
CrowdStrike Holdings Investment Narrative Recap
To own CrowdStrike today, you need to believe Falcon can remain a core security platform as customers secure cloud, identities and now AI agents, and that high subscription margins will support strong cash generation. Falcon's new availability in the OpenAI Marketplace could reinforce the near term AI security catalyst by plugging CrowdStrike directly into enterprise AI budgets, but it does not change the key risk that current expectations already bake in very strong future ARR and earnings delivery.
Among recent developments, the expansion of Falcon Flex stands out next to the OpenAI Marketplace news. Flex is designed to deepen customer commitment across Falcon's 30 plus modules, and the ability for OpenAI enterprise customers to route existing AI commitments into Falcon fits that theme of heavier, multi year engagements. Together, they highlight how much of the bullish case rests on CrowdStrike converting AI centric offerings into higher ARR per customer without masking volatility behind non GAAP metrics.
Yet, while enthusiasm is high, investors should also keep in mind the risk that heavy reliance on long term Flex style commitments can cut both ways if...
Read the full narrative on CrowdStrike Holdings (it's free!)
CrowdStrike Holdings' narrative projects $9.9 billion revenue and $1.1 billion earnings by 2029. This requires 22.2% yearly revenue growth and about a $1.1 billion earnings increase from $45.0 million today.
Uncover how CrowdStrike Holdings' forecasts yield a $235.67 fair value, a 10% downside to its current price.
Exploring Other Perspectives
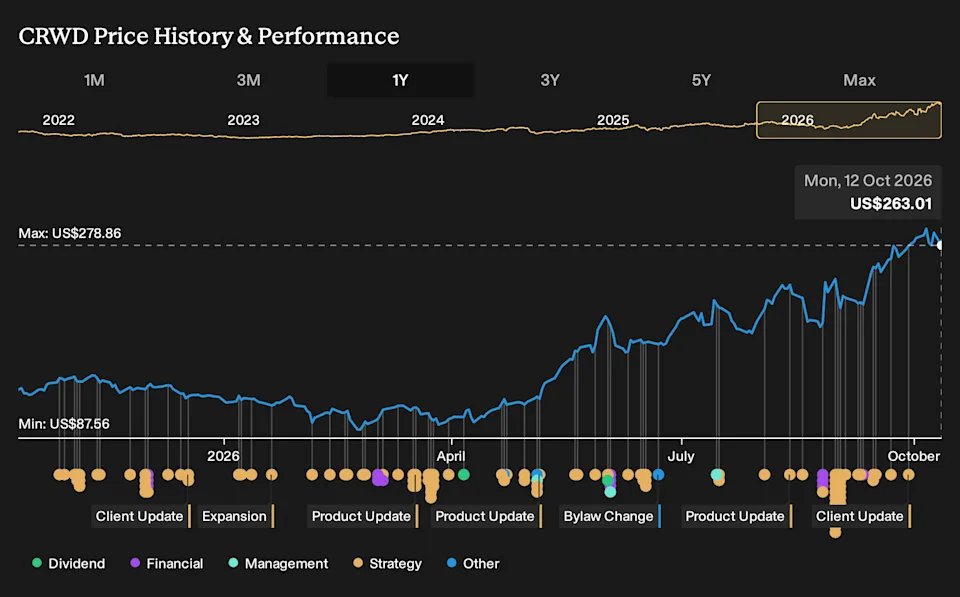
Some of the most optimistic analysts were already assuming revenue could reach about US$11.2 billion and earnings US$1.8 billion by 2029, so this kind of AI marketplace news may either support their view of CrowdStrike becoming a default AI security layer or highlight how much depends on executing that vision in a field where opinions, and outcomes, can differ widely.
Explore 11 other fair value estimates on CrowdStrike Holdings - why the stock might be worth over 2x more than the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
A great starting point for your CrowdStrike Holdings research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
Our free CrowdStrike Holdings research report provides a comprehensive fundamental analysis summarized in a single visual - the Snowflake - making it easy to evaluate CrowdStrike Holdings' overall financial health at a glance.
Ready For A Different Approach?
Right now could be the best entry point. These picks are fresh from our daily scans. Don't delay:
Uncover the next big thing with 11 elite penny stocks that balance risk and reward.
AI is about to change healthcare. These 33 stocks are working on everything from early diagnostics to drug discovery. The best part - they are all under $10b in market cap - there's still time to get in early.
The future of work is here. Discover the 91 top robotics and automation stocks leading the charge in AI-driven automation and industrial transformation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Companies discussed in this article include CRWD.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email [email protected]