
Nvidia Isn’t the Whole AI Story. This Stock Could Prove It
Price Targets desk. Editor: Vandita Jadeja.
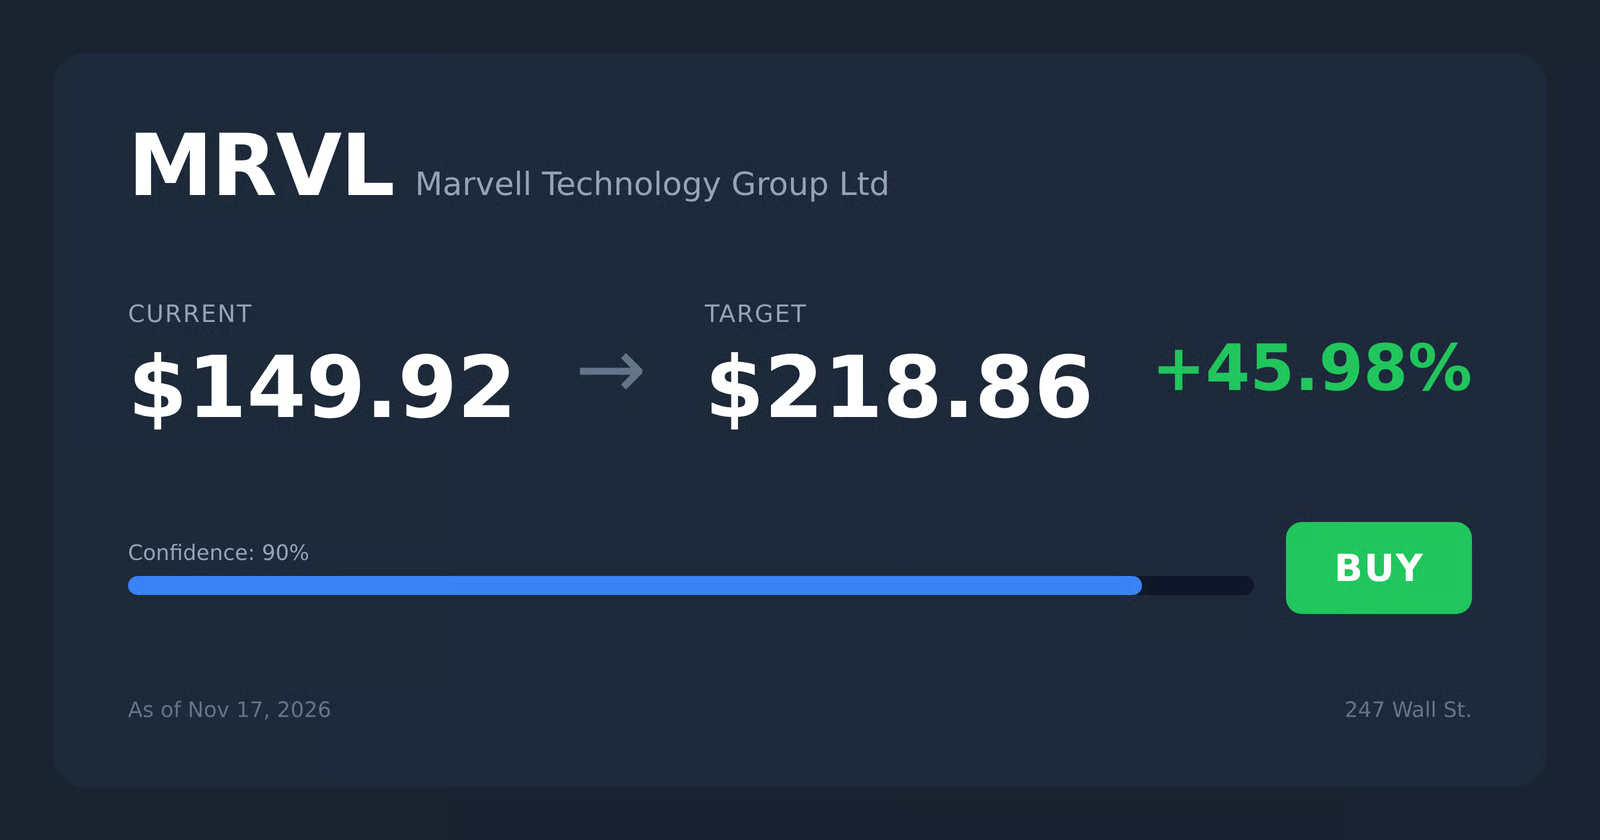
Our own financial model gives Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) a price target of $232.41 over the next 12 months. The stock last closed at $168.80. This means our target suggests the stock could rise by 37.69%. Our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $168.80 |
| 24/7 Wall St. Price Target | $232.41 |
| Upside/Downside | 37.69% |
| Recommendation | BUY |
| Confidence Level | 90% |
Marvell makes the parts that help AI data centers connect and share information. These include custom XPUs, 800G and 1.6T optical products, and 51.2T Ethernet switches. Data Center sales made up 79% of the company's revenue last quarter. Management expects revenue to reach about $18 billion in fiscal 2028. The stock trades at about 21 times its expected earnings.
Lumentum Deal Sends Shares Down 39% in a Month
Marvell shares fell 39.04% over the past month. However, they are still up 91.03% since the start of the year and 1.42% over the past week. The stock is 48.8% below its highest price over the past 52 weeks, which was $329.73.
View the full MRVL chart and data →The main reason for the drop was an all-stock deal announced on November 2. Marvell agreed to buy Lumentum (NASDAQ:LITE) in a deal with an implied enterprise value of $115 billion. Marvell shares fell 13% that day. Barron's described the period as a historically bad week for both stocks. The deal is expected to close in the first half of 2028.
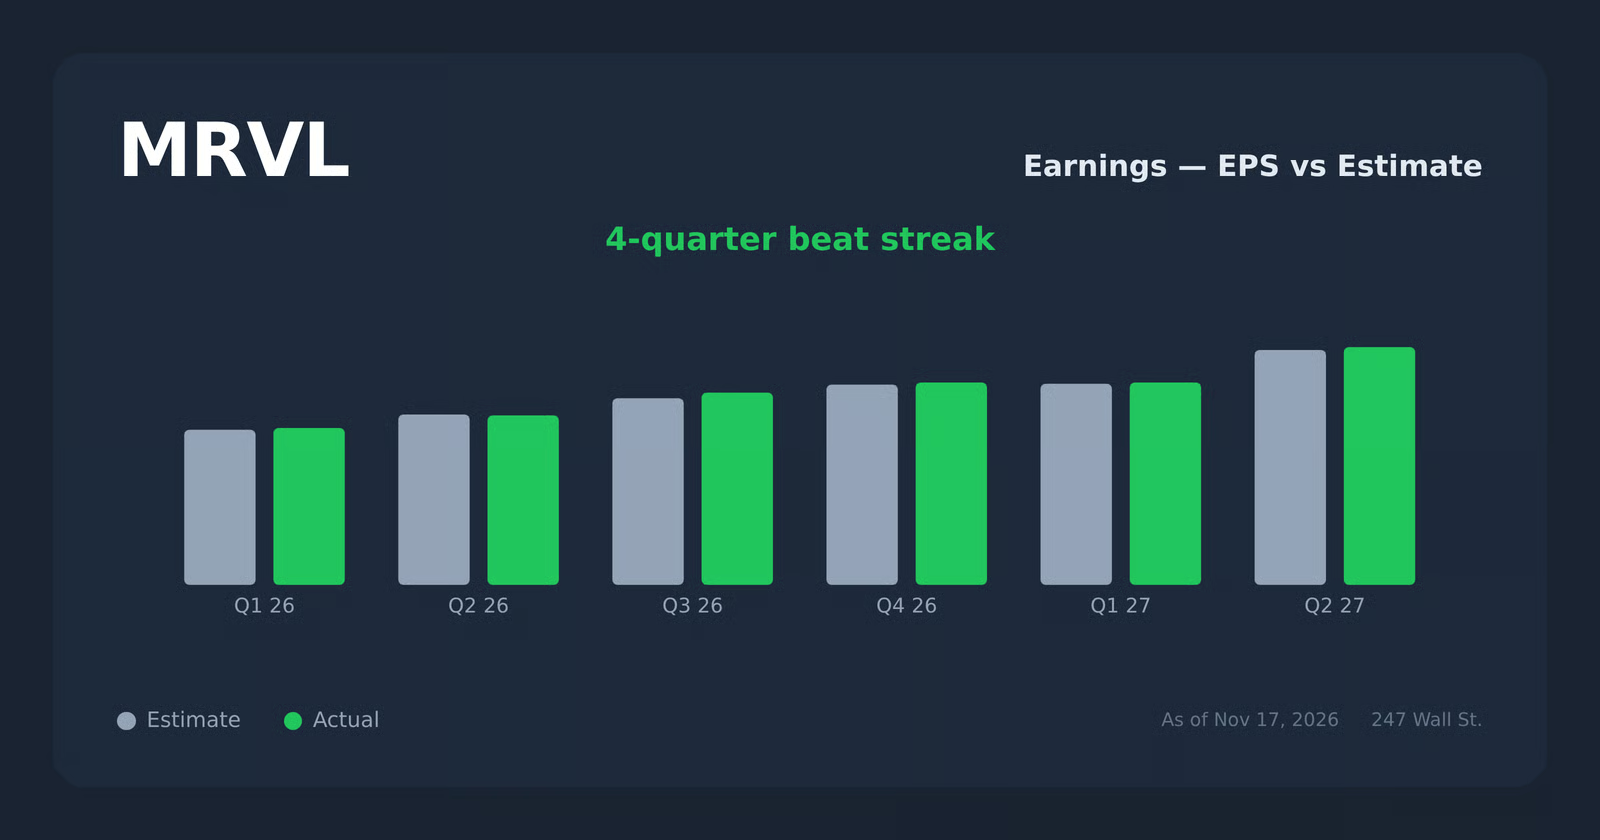
Marvell's business results remained strong. In the second quarter of fiscal 2027, revenue was $2.7393 billion. That was a 36.55% increase and was higher than the expected $2.7068 billion. Adjusted earnings per share, which do not include certain costs, were $0.94. This was also higher than the expected $0.9289. Marvell expects third-quarter revenue of $3.150 billion.
Why Optimistic Investors See $351 and Beyond
The optimistic price estimate is $351.61. Management raised its fiscal 2028 revenue forecast from $16.5 billion. It also expects revenue from custom products to more than double.
Marvell has also expanded its partnership with Google's parent company, Alphabet (NASDAQ:GOOGL). The agreement includes a warrant for up to 7% of Marvell's shares. CEO Matt Murphy said, “Whatever you’ve modeled previously for custom numbers prior to the warrant definitely goes higher.”
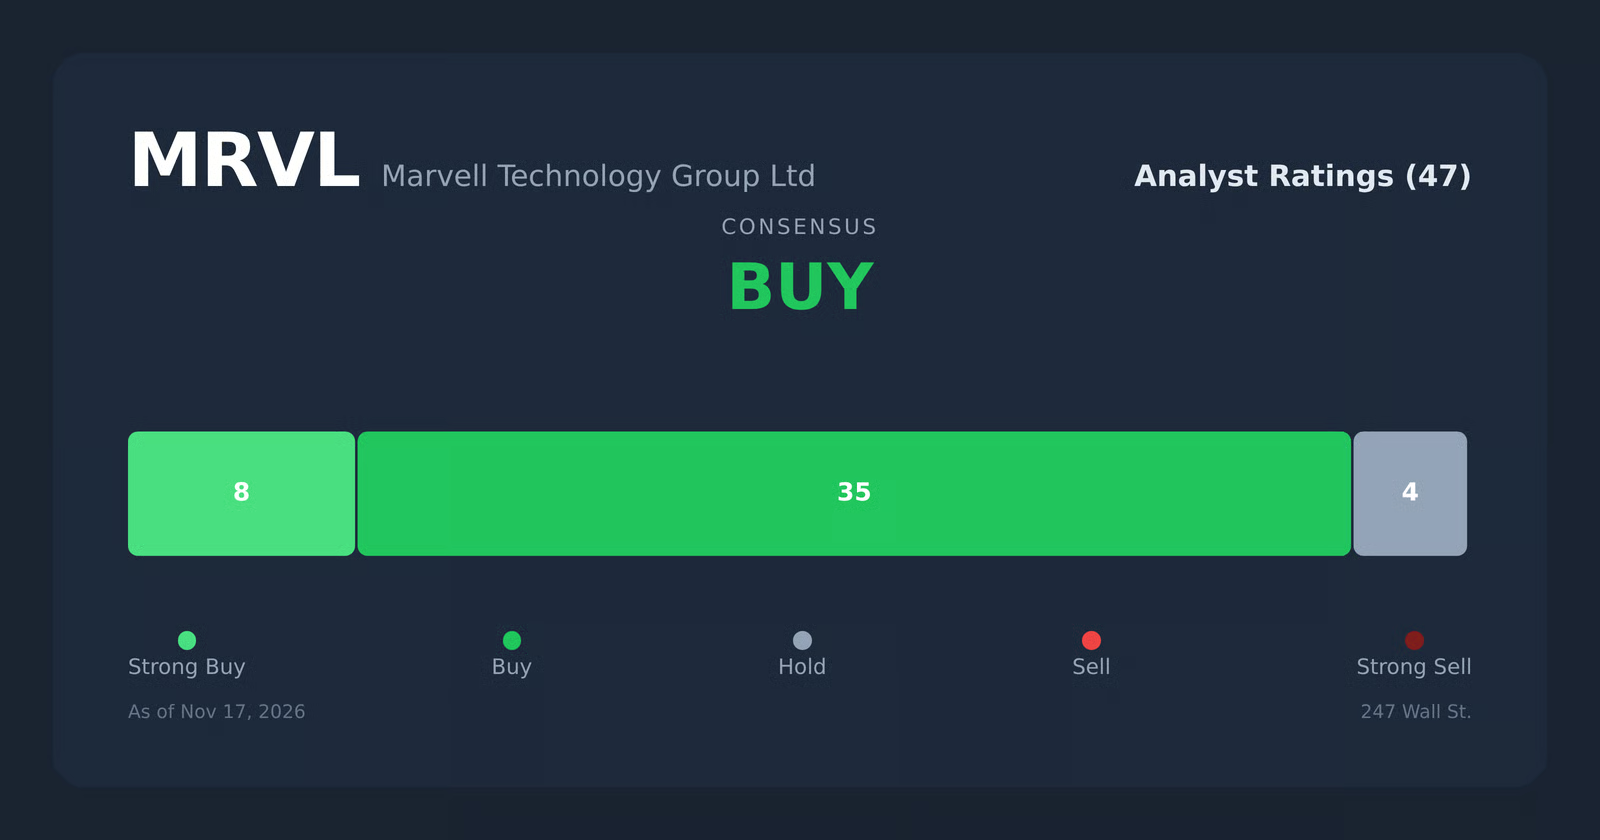
The average price target from analysts is $310.94. Their ratings include 8 Strong Buy, 35 Buy and 4 Hold ratings.
Share Dilution and Customer Dependence Are Major Risks
The pessimistic price estimate is $181.75. Under the Lumentum deal, Lumentum shareholders will receive 4.5 Marvell shares for each Lumentum share they own. This will increase the number of Marvell shares. The Google warrant could add further dilution. Company filings also point to risks from depending heavily on certain customers, trade restrictions involving China, and $4.963 billion in long-term debt.
Marvell's GAAP earnings per share were $0.33, below its adjusted earnings per share. Much of the difference comes from items that do not involve cash payments. One example was a $331.8 million charge for contingent consideration in the first quarter. The company is also increasing production of custom products, which is putting pressure on its gross profit margin. However, its adjusted operating margin still grew to 36.6%.
How Marvell Compares to Broadcom and NVIDIA
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Marvell | 21x | 36.5% |
| Broadcom | 17x | 85.5% |
| NVIDIA | 11x | 105.9% |
The company most similar to Marvell in custom chips and networking is Broadcom (NASDAQ:AVGO). Its AI semiconductor revenue rose 221% to $16.70 billion. Broadcom is growing faster than Marvell and its stock trades at a lower price compared with expected earnings. This means Marvell must deliver the faster growth that management expects to justify its higher stock valuation.
NVIDIA (NASDAQ:NVDA) is both a company to compare with Marvell and a business partner through NVLink Fusion. NVIDIA's Data Center Networking revenue rose 138%. This shows that AI spending supports more than just GPUs. It also creates demand for companies that supply power, cooling and networking equipment. We covered these suppliers in a free report about seven AI infrastructure companies that do not make chips. Compared with its competitors, Marvell's stock looks more expensive based on expected earnings. Our price target is well below the average analyst target, so we believe it is reasonable.
What Could Move Marvell After the Lumentum Selloff
I am keeping our 24/7 Wall St. price target at $232.41. Our recommendation remains a buy with high confidence. The main reasons are the higher fiscal 2028 revenue forecast and the fact that the stock lost more than one-third of its value in one month.
The positive outlook will become stronger if Marvell meets its third-quarter earnings forecast of $1.10 per share and revenue from custom products starts growing faster. The outlook will become weaker if the costs of combining Marvell and Lumentum's businesses, or cuts in spending by large cloud computing companies, hurt expected results. After the recent drop, the stock is trading below our price target.
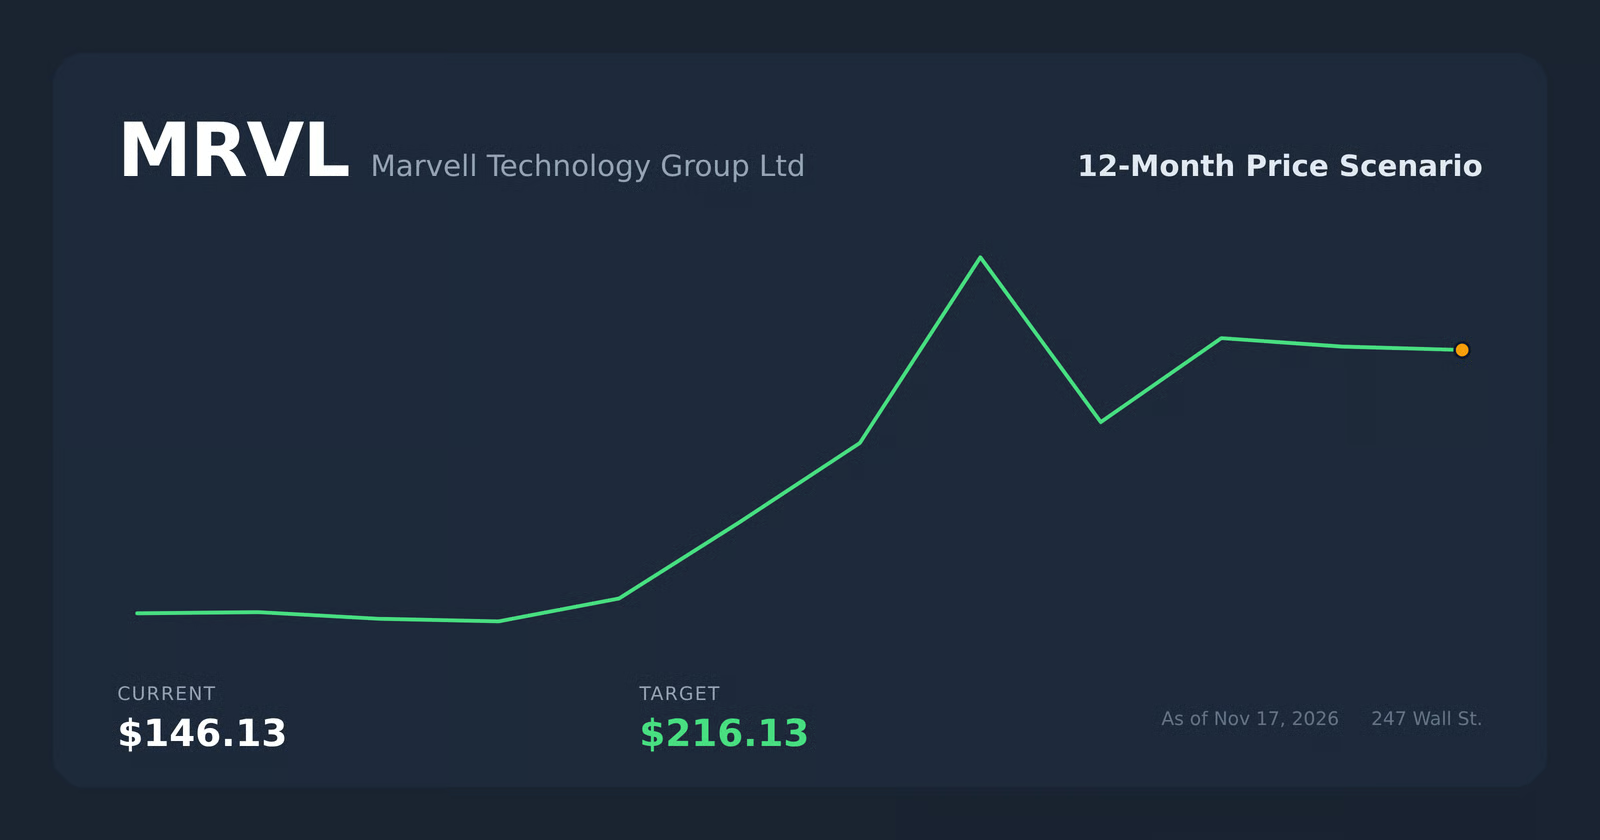
Our model estimates where Marvell's stock could trade if its current growth trends continue.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $166.43 |
| 2027 | $239.90 |
| 2028 | $278.83 |
| 2029 | $342.39 |
| 2030 | $377.76 |
Marvell must continue to do well with custom chips and optical products for these estimates to come true. The biggest factors that could change the outcome are how well the Lumentum deal works and how much large cloud computing companies continue to spend.
Contact [email protected] with any questions or corrections.