
Broadcom’s AI Revenue is Contracted to Double in 2027, So I’m Buying
My investment in Broadcom (NASDAQ:AVGO | AVGO Price Prediction) keeps getting bigger. Each earnings report gives me another reason to keep the stock. The latest reason came in September, when company leaders said they had secured enough supplies to double AI revenue again in fiscal 2027.
My main idea is simple: the world's biggest companies that build AI models are working with Broadcom to design their own chips. These partnerships could bring years of steady demand. I want this kind of clear business outlook in my retirement account.
A Fiscal 2027 AI Business I Cannot Ignore
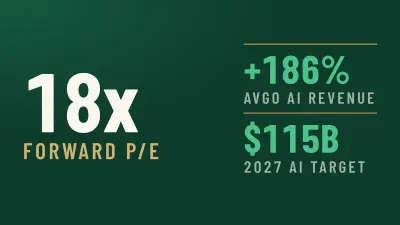
Broadcom raised its forecast for AI revenue in fiscal 2026 to $58 billion, an increase of 186%[1]. Then CEO Hock Tan explained what could happen next: “In 2027, we have secured the supply to again double AI revenue to approximately $115 billion. Our demand actually exceeds this outlook, and we will work to improve supply.”[1]
Tan also said that “Anthropic is on track to become our largest XPU customer in 2027.”[1] OpenAI plans to use its Jalapeno chip in a system with 1.3 gigawatts of power in 2027. Google's parent company, Alphabet (NASDAQ:GOOGL), has also reached a deal lasting several years. It covers “multi-tens of billions of dollars of TPUs annually over the next several years.”[1]
Three Reasons I Feel More Confident
The company is already growing quickly. Revenue in the third quarter reached $29.591 billion, up 85.5%[2]. Revenue from AI chips reached $16.7 billion, up 221%. Adjusted earnings per share, also called non-GAAP EPS, were $3.32[2]. That was higher than the expected $3.24. Broadcom has now beaten earnings estimates for 9 quarters in a row. Company leaders expect fourth-quarter revenue to be about $34.8 billion[2].
The company keeps bringing in cash. Free cash flow reached $13.665 billion[2], equal to 46% of revenue. The company used that cash to pay $3.1 billion[1] in dividends and pay off $5.6 billion in long-term debt in just one quarter. Its VMware software business also provides a steady source of income. Revenue from Infrastructure Software grew 29%[2] to $8.752 billion, with a gross profit margin of 94%[1].
The dividend is growing, and the share price looks reasonable. Broadcom raised its dividend by 10% to $0.65 per share[3]. This is the company's 15th yearly dividend increase in a row since fiscal 2011. At $333.40, the stock is down 3.14% since the start of the year and trades at 18 times its expected future earnings.
Why I Choose Broadcom Instead of NVIDIA or AMD
Shares of NVIDIA (NASDAQ:NVDA) are cheaper, trading at 10 times expected future earnings. But because I invest to earn income, I prefer Broadcom's 0.71% dividend yield to NVIDIA's 0.17%. I also want to invest in companies that are moving toward custom-made chips. Broadcom says its Jalapeno chip can run advanced AI models at half the cost of a GPU.[1]
AMD (NASDAQ:AMD) trades at 32 times expected future earnings and does not pay a dividend. I am not choosing it.
One Risk That Could Hurt My Investment
Six major customers account for much of Broadcom's expected AI growth. Their plans to build new facilities depend on having enough land, electricity and data center buildings. Tan openly discussed this problem: “The question in our minds sometimes is, even as we ship the chips, will they be deployed on a timely basis?”[1] Profit margins are also falling. Broadcom expects its gross margin to be about 73% in the fourth quarter, compared with 78% a year earlier. This is happening because XPUs, which have lower profit margins, are becoming a bigger part of sales.
I am willing to accept this risk because the operating margin should stay close to 66%[2] of revenue. The company also has $59.6 billion[1] in fixed-rate debt, with an average interest rate of 4%. Its cash flow is enough to cover these payments.
Why I Keep Buying Before December 9
Broadcom will report its fiscal 2026 results on December 9, 2026[4]. I will keep watching the stock for its next dividend decision and news about chip supplies. Company leaders have already said they expect AI revenue to reach $230 billion in fiscal 2028.[1] When a company says that customer demand is greater than the supplies it can secure, it stays high on my list of companies to research. We also studied what the biggest successful AI chip companies looked like in their early days in a free guide here.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer who has experience with both individual and professional investing. He has written for InvestorPlace and worked at BNY Mellon and Bernstein. These roles give him a view of both everyday investors and Wall Street professionals.
Alex has an MBA from George Washington University. He has worked in several industries, including online shopping, education and translation. This wide range of experience helps him explain difficult financial topics in ways that everyday investors can understand. His writing is friendly, useful and focused on long-term investing and holding investments for years.
At 247 Wall St., Alex writes articles that are easy to understand and useful. His goal is to help readers make better choices about their money.