Anthropic pushes toward an IPO while CoreWeave's debt spooks Wall Street
CoreWeave's default insurance costs just topped a level traders treat as distress. Anthropic, which actually buys CoreWeave's compute, is heading the other way, toward Nasdaq.
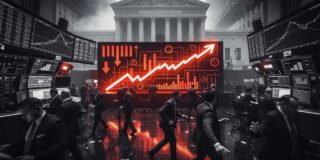
You can see the split in the AI trade happening in two numbers released the same week. CoreWeave's five-year credit default swap spread pushed past 1,000 basis points in mid-October, a threshold traders use to price in roughly a 60% chance the company defaults within five years, according to CNBC. Its 9.75% notes due 2031 were yielding as high as 15.78%. Meanwhile, Anthropic is moving toward a Nasdaq listing. Bloomberg and other outlets now expect it to headline the fourth-quarter IPO pipeline, built on a quarter where the company actually turned a profit.
Anthropic filed a confidential S-1 with the SEC on June 1, and reporting since then points to an October or fourth-quarter 2026 listing led by Goldman Sachs, JPMorgan and Morgan Stanley. The company's Q2 2026 revenue came in above $11.5 billion, roughly 14 times what it booked in the same quarter of 2025, and it posted $559 million in adjusted operating profit, its first profitable quarter, according to reporting from the Financial Times and other outlets tracking the filing. By the end of July its annualized run rate had climbed to $65 billion, up from $47 billion in May and $9 billion at the end of last year. That's a steep curve. It makes a $965 billion Series H valuation, closed in May, look almost conservative to the bankers now pricing the deal at $2 trillion or more.
CoreWeave tells a very different story, and it's one that matters to Anthropic directly: CoreWeave is one of the companies renting it GPU capacity. CoreWeave has piled up more than $51 billion in debt and lease obligations financing the data centers behind its AI cloud business, and interest expense alone ate more than a quarter of its revenue last quarter. Its backlog, a reported $100 billion in take-or-pay contracts with Meta, OpenAI, Microsoft and Anthropic among others, is real. Whether that backlog converts to cash fast enough to service the debt is the question bond traders are now betting against. The CDS spread jumped from roughly 368 basis points on October 6 to north of 1,000 within the same month, a move Global Markets Investor and other trackers flagged as a sign of outright credit distress, not just nerves.
Frankly, this is the clearest evidence yet that investors are no longer willing to treat "AI company" as one basket. CoreWeave sells raw compute. It borrows heavily to build the data centers that compute runs on, and it is exposed to every customer's capital discipline, including Anthropic's. Anthropic sells the model layer directly to enterprises and consumers, carries far less debt, and just posted a profitable quarter doing it. One is a landlord with a mortgage. The other is collecting rent and keeping some of it.
CoreWeave's 2032 unsecured notes sank below 80 cents on the dollar as five-year credit default swap spreads nearly doubled, from 368 to 643 basis points, in a single week this October. - CoreWeave bond yields jump to fifteen percent - AI debt crisis signals corporate distress ahead
That doesn't mean the infrastructure layer is doomed and the model layer is safe. Oracle and SpaceX have both seen their own CDS spreads widen to records this month, according to the same market trackers watching CoreWeave, which tells you the skepticism around AI-linked debt is broader than one company's balance sheet. But it does mean capital is rotating, and Anthropic's timing couldn't be better for it. The third quarter of 2026 was a weak one for new listings generally: Renaissance Capital counted just 31 IPOs raising $34.9 billion, and strip out the SK hynix mega-deal and proceeds fall to $8.4 billion. Against that backdrop, a profitable, fast-growing AI company willing to go public looks less like one listing among many and more like the listing the whole fourth quarter is waiting on.
There's a competitive angle here too. OpenAI had once eyed a fall 2026 listing of its own and has since pushed that timeline to 2027, according to multiple reports tracking both companies' IPO plans. If Anthropic lists first, it gets to set the public-market comparable that OpenAI will be measured against for a year, on terms Anthropic chose. Bankers don't get many chances to price a company at this scale while its only real rival is sitting on the sidelines.
None of this erases the risk sitting under the whole AI buildout. Around $800 billion is expected to go into AI infrastructure in 2026 alone, climbing past $1 trillion in 2027, and CoreWeave's situation is a live test of what happens when the bill for that buildout comes due before the revenue catches up. Anthropic doesn't carry that bill. For now, that difference is worth a lot more than a shared label.
Nscale's $35 Billion IPO Is Wobbling Because Its Data Centers Aren't Ready • Bank of America Hired 1,000 Contractors to Fix Bugs an AI Agent Found • Meta released an open AI model so big it needs 1TB of Mac memory
This article is posted in AI News, check it out for more related stories.