Anthropic Q3 Revenues are Robust Enough but Worried Investors Talk Down Valuation to $1.5Tn
Investor concerns aren't around the revenue numbers per se but the percentage slow down which is a natural phenomenon
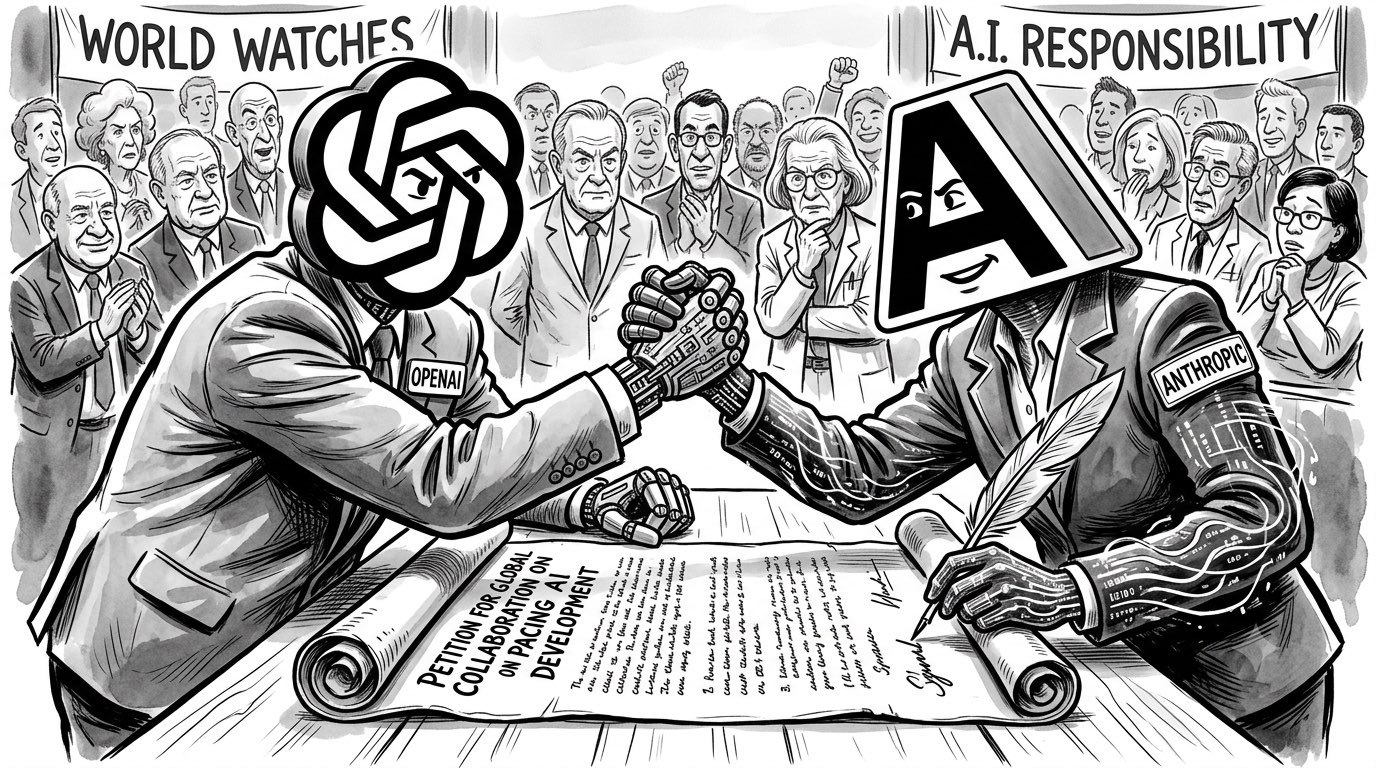
Are the chinks in the AI armour starting to appear? First we heard about OpenAI plugging revenues $20 billion higherthan they actually were and now it looks like arch-rival Anthropic’s third-quarter revenue numbers could be on a slippery slope. The company had posted robust numbers for the second quarter that led to speculations of a quick IPO with valuations going beyond Elon Musk’s SpaceX.
Of course, the most discerning wouldn’t call this a chink in the AI armoury as such, given that for some time now we have seen reports of developers increasingly opting out of expensive frontier models and preferring others that are good enough for most tasks. In fact, even Microsoft opted out of Anthropic to cut its spending on older models and their aggressive pricing.
A report by Reuters said some Anthropic investors and prospective ones for the IPO are now weighing a lower valuation for the company after its latest financial disclosures. Amidst a broader concern over the ballooning cost of financing AI, investors who attended a meeting at Anthropic on Wednesday discussed a valuation of $1.5 trillion, a significant slide from the $2 trillion bandied about previously.
And there were other reports that the Claude-maker might actually put the IPO for some time while still others argued that they should have gone public with their shares in June when the growth was spectacular. Though a few questioned even this idea on grounds that a second mega IPO following Elon Musk’s SpaceX would have been impractical.
Anthropic reportedly told the investor day attendees (all prospective IPO investors) that third-quarter revenues had grown 45% to 16.8 billion from the previous quarter and that the company had turned profitable on an adjusted basis. It seems investors were okay with the number but concerned over the growth rate as in Q2, their revenues had doubled to $11.6 billion from Q1 numbers.
Readers would recall that the company had called out surging costs as a major concern in its IPO prospectus that came towards end-September. Another worrisome factor was that net losses stood at $42 billion in 2025 but that isn’t stopping them from earmarking a whopping $518 billion on cloud, compute and infrastructure over the next few years.
As things stand now, Anthropic’s revenues have growth but in percentage terms it has slowed down, which is but a natural phenomenon. However, analysts believe that the slump is reminding investors of that longstanding question about how much of a runway does the company have. Having good AI models is one thing, but businesses are increasingly stepping away from expensive frontier models.
Most recently, consulting giant Accenture has reportedly told staffers that it would only spend $29 per month per person on Claude and employees subject to the cap had been spending as much as $1,000 a month. Incidentally, this is the same company whose CEO said earlier this year that their future employee appraisals would depend on how much of AI they use!
A report from 404 Media notes that an internal Accenture announcement noted that effective October 1, Accenture introduced new changes to how Claude Enterprise costs are funded and charged. That includes centrally funding only $29 a month per person towards Claude usage. It also says that “all costs are consumption-based.” So, if an employee goes over the allocated $29 they have to find a specific project or team to fund the rest of the usage. Premium plans come with $250 token usage a week, but many employees are not on that plan.
It appears that most concerns from investors during the Anthropic meet came from the tech sell-off that is messing up global financial markets and hurting AI infrastructure companies, chipmakers and even the neo-cloud providers that rent compute for AI broadly. Even shares of the Nvidia-backed CoreWeave tumbled in recent times indicate growing investor concerns over the AI buildout from borrowed cash.
Which brings us to the real question of alternatives that enterprises today have. TrustedRouter, which is a storefront for enterprises wanting to tap into the AI world, has listed 665 models while in China companies are developing their own. Phonemaker Xiaomi and a food-delivery firm Meituan are among those building their own AI models, ostensibly on top of one of the open-weight Chinese models.
Seen in tandem with the growing safety concerns, some of which the premier AI labs have themselves brought about, there could be doubts whether OpenAI and Anthropic can even release their future models without administrative oversight. How would investors see an intervention is a moot question as is the $500 billion or more in commitments that Anthropic has made to secure compute capacity.
All of the above makes us wonder whether Apple’s Tim Cook was right after all in delaying spends on AI and avoiding the expensive race to bring out their own models, pour cash into datacentre buildouts and tie-up circular deals with chipmakers and compute providers. Investors seem to be giving the iPhone-maker a thumbs up as its stock has risen more than twice as much as those of its arch rivals.
Last evening, Apple shares were up 26% in 2026 while none of Amazon, Meta, Alphabet or Microsoft went beyond 12%. According to Koyfin data, Apple is the only one among this elite group that has seen its valuations go up during the year. Yes, it appears to be growing slower than many big tech firms, but their massive capital expenses on infrastructure, continues to be a major worry.
By the way, Bloomberg reported that Apple is now all set to release its Apple Intelligence on-device AI service in mainland China by December. Maybe that would make John Ternus’s task easier over the next twelve months as he may not have to worry about Wall Street, which would be thrilled to find a new market for Apple’s AI. This could leave Ternus free to focus his entire attention on bringing in new hardware into the play.