
Anthropic offers Blackstone a double-digit yield to fund its chip habit
Even the AI lab Wall Street treats as the safe bet is now paying junk-bond money to keep its chips coming.
Anthropic has offered Blackstone a coupon of more than 10% to anchor a $9 billion junior slice of a $60 billion debt package arranged by Broadcom, according to a Financial Times report published October 16. The senior $42 billion piece of that package covers roughly a third of a far bigger number buried in Anthropic's IPO paperwork: a $125.2 billion, five-year commitment to lease Google's tensor processing units.
Put that next to what similarly rated borrowers pay in the public bond market right now, about 7%, and the gap tells you something. Anthropic isn't struggling. It's the company everyone points to as proof the AI boom has at least one real business behind it. And it's still paying double digits to get a junior lender to show up.
Broadcom's role here is the part worth sitting with. It designs and supplies Anthropic's chips. It leases them to Anthropic. It has agreed to lend Anthropic up to $42 billion through convertible notes that can turn into Anthropic equity. And it's the one arranging and guaranteeing the $60 billion debt package that Wall Street banks are now syndicating. Four jobs, one counterparty, one deal. Anthropic's own prospectus flags this directly, warning of "potential conflicts of interest" because decisions Broadcom makes on pricing and equipment availability could affect Anthropic's ability to actually build out the infrastructure it's borrowing all this money for.
This financing push isn't happening in a vacuum. The same week Blackstone's term sheet surfaced, CoreWeave's bonds were trading toward 15%, a level the market generally reserves for companies it thinks might not make it. CoreWeave's 9.625% notes due 2032 climbed from around 13.4% at the start of October to above 15% by October 14, and the stock fell as much as 16% in a single session. Venture capitalist Chamath Palihapitiya posted a chart of the move and called it a private-credit bubble; Elon Musk replied with one word, "Yikes." CoreWeave carries roughly $52 billion in debt, and its Q2 interest expense, about $640 million, already outran its adjusted operating income for the quarter.
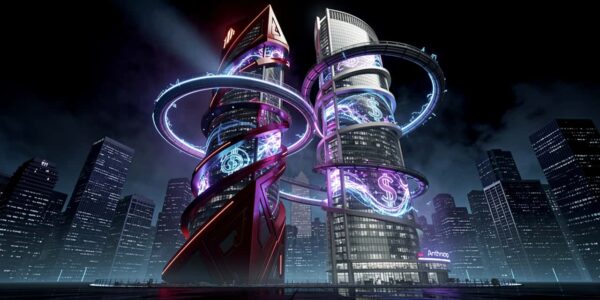
Anthropic's IPO filing reveals Broadcom has agreed to lend the AI lab up to $42 billion in convertible notes, covering roughly a third of its $125.2 billion five-year TPU lease commitment. The arrangement ties Broadcom's balance sheet directly to Anthropic's compute buildout just as the company heads toward a public listing. - broadcom lends anthropic billions before IPO - anthropic convertible notes from broadcom deal
Anthropic is not CoreWeave. It just raised $65 billion in a Series H round in May at a $965 billion valuation, led by Altimeter Capital, Dragoneer, Greenoaks and Sequoia, and it's reportedly preparing an IPO as soon as mid-November at a valuation FT and other outlets have put as high as $2 trillion. None of that changes what private lenders are charging for the riskiest piece of AI infrastructure debt in late 2026.
That's the real story under the headline. A company with Anthropic's balance sheet and growth trajectory should, in a normal credit market, pay close to investment-grade rates on a well-structured lease financing. Instead the junior slice of its chip debt is pricing like high-yield paper, because the asset underneath it, depreciating TPUs with uncertain resale value if Anthropic's growth ever stalls, is exactly the kind of collateral that's making private credit investors nervous across the entire AI buildout. Blackstone and Apollo priced a similar structure for Anthropic back in June, a $35 billion deal where the senior tranches, backed by a Broadcom residual-value guarantee, carried a 5.75% coupon while the unguaranteed $4.5 billion junior piece went out at 8.5%. Four months later, the junior price for essentially the same kind of risk has climbed past 10%.
Frankly, that trajectory is the whole point. Lenders aren't repricing because Anthropic's business got worse. They're repricing because the market watched CoreWeave's bonds blow out and decided every AI infrastructure loan, even one standing behind the best-capitalized lab in the industry, needs a bigger cushion. Chainalysis-style sector math doesn't apply here, but the logic is the same one that's rattled every corner of AI credit this month: when the marginal buyer of risk gets scared, even the safest-looking borrower pays for it.
TypeSafe's Jev becomes Vercel AI Gateway's fastest-adopted model ever • PS5LM Plus now runs AI models natively on a jailbroken PS5's GPU • Google's Universal Cart Goes Live and Retailers Are Already Pushing Back
This article is posted in AI News, check it out for more related stories.
Join the discussion
 AI
TypeSafe's Jev becomes Vercel AI Gateway's fastest-adopted model ever
 AI
PS5LM Plus now runs AI models natively on a jailbroken PS5's GPU
 AI
Google's Universal Cart Goes Live and Retailers Are Already Pushing Back