
Anthropic’s Net Cash: $23B With Its Notes, $132B Without
Anthropic filed its S-1 registration statement with the SEC on 26 October 2026. It shows that on 30 June 2026, Anthropic had $131.7 billion in cash, cash equivalents and short-term investments. It also had one large liability: $108,566 million in convertible notes payable. If we count these notes as debt, Anthropic has $23.1 billion in net cash, based on our calculations. If the notes turn into shares at the IPO, as the filing describes, most of this debt would disappear from the balance sheet, based on our calculations.
A chart by Sikand Media, posted on X on 26 October and shared with us on 27 October, ranks Anthropic second among US non-financial companies for net cash after its IPO. The chart estimates about $200 billion, behind Berkshire Hathaway. Its footnote says, “Values are illustrative estimates; debt treatment may differ.” How the debt is counted makes all the difference. People on X also disagree about how much cash Anthropic really has available.
Video explainer · Anthropic’s S-1
This 16:9 video explains Anthropic’s net cash and its notes from Amazon. The narration is based on this article and three related FourWeekMBA articles.
The main point: In our reading, Anthropic’s net cash depends on one line in its S-1: $108.6 billion in Amazon convertible notes, measured at fair value, even though their principal is $6.2 billion. The filing says the notes turn into shares at the IPO, subject to Amazon’s ownership limit.
What the Balance Sheet Shows
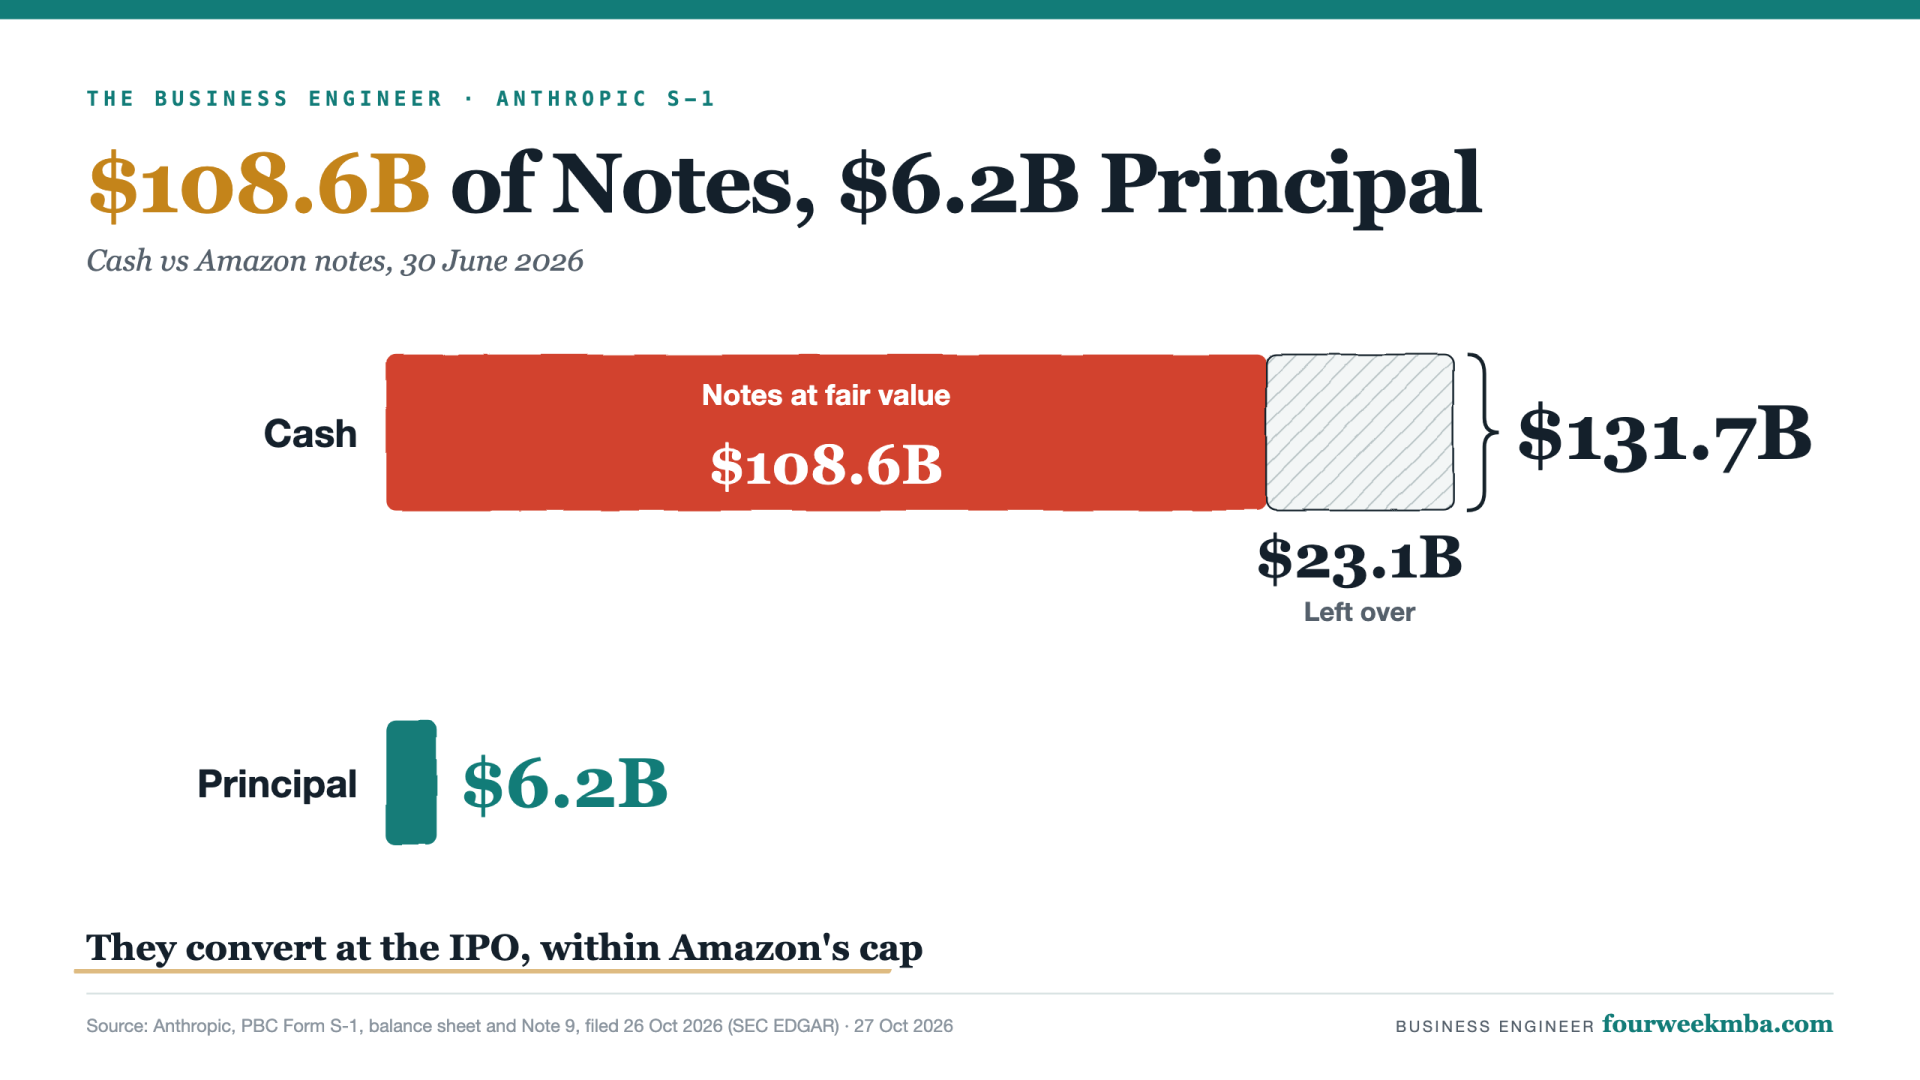
Anthropic’s S-1 balance sheet shows that on 30 June 2026, the company had $112,389 million in cash and cash equivalents, plus $19,262 million in short-term investments. Together, these totaled $131,651 million. Its convertible notes payable were $108,566 million, and its total liabilities were $117,467 million.
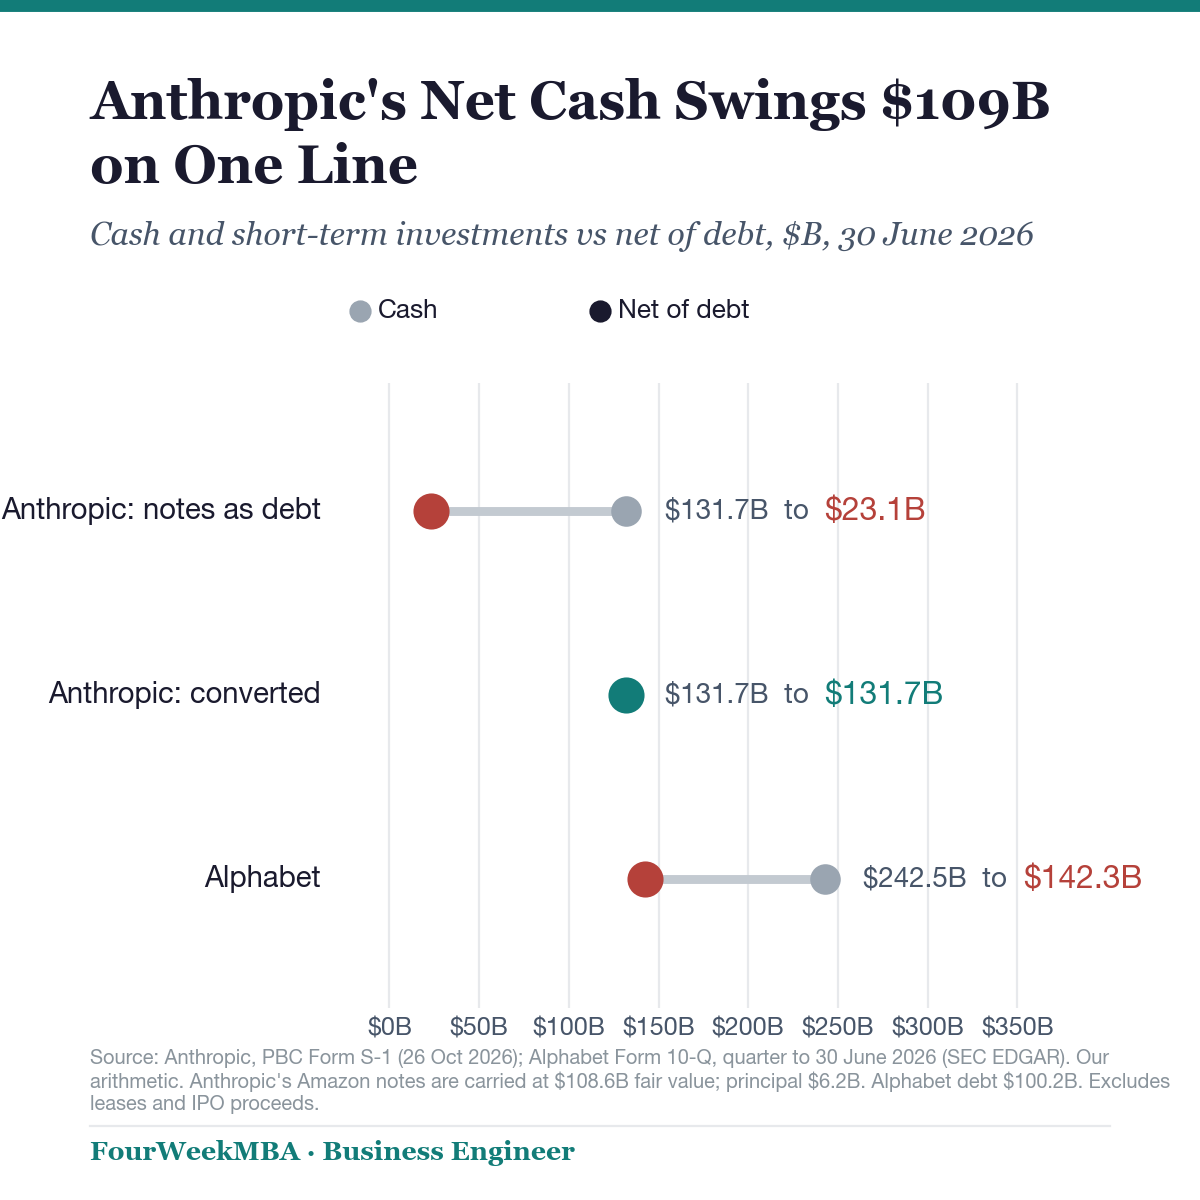
The filing says Anthropic had “no borrowings drawn under the revolving credit facility” on 30 June 2026. It had $3.2 billion available through this facility. If we subtract only the convertible notes from cash and short-term investments, the result is $23.1 billion, based on our calculations. Neither net-cash figure counts leases as debt.
What Was Posted on X
The most surprising figure in the $ANT S-1 is that Anthropic will have more cash than any other tech company in the world.
— Michael Sikand (@michaelsikand) Oct 26 18:47
Michael Sikand (@michaelsikand) posted that, according to his reading of the $ANT S-1, the most surprising fact is that Anthropic will have more cash than any other tech company in the world.
The idea that Anthropic is financially safer than Amazon because it has $132 billion in cash shows a basic misunderstanding of balance sheets that are shaped by complex funding arrangements:
— Dawson Lee | Silicon & Infra Alpha (@lidaosen) Oct 27 00:11
Where the Cash Comes From: Amazon’s cash comes from free cash flow generated by its cloud business, Prime and delivery network. Anthropic’s $132 billion in cash came from $140 billion in outside preferred shares, SAFEs and convertible debt. Its operating cash flow is deeply negative.
Promises to Spend: Looking only at the assets on the left side of a balance sheet ignores promises and other obligations. Anthropic’s S-1 disclosures show more than $230 billion in long-term, non-cancellable computing commitments: $110 billion to Amazon AWS and $120.5 billion to SpaceX. The post says the cash is legally set aside to pay for these commitments.
Money Moving in a Loop: Much of this money follows a closed loop. Large tech companies and private lenders provide money to AI companies. Those companies hold the money for a time and then pay AWS for cloud computing services.
When a company has $132 billion in cash but more than $230 billion in fixed spending commitments, it does not have an enormous financial safety net. It faces several years of spending that may require more funding or enough cash from business operations before the money runs out.
Li Daosen (@LiDaosen) argued that Anthropic’s $132 billion in cash came from preferred shares, SAFEs and convertible debt. In his reading of the S-1, the money is set aside for more than $230 billion in computing commitments. He disagreed with the view that Anthropic is financially safer than Amazon.
Whose Notes They Are
The notes outstanding on 30 June belonged to Amazon. The S-1 says the rollover note under the 2023 Amazon agreement “remained outstanding with an aggregate principal amount of approximately $2.2 billion”. It also says “all notes issued under Amazon 2024 NPA remained outstanding with an aggregate principal balance of $4.0 billion.” Together, their principal totaled $6.2 billion, based on our calculations.
The $108.6 billion figure is the notes’ fair value, not the amount Anthropic must repay. At an IPO, the notes convert into Class N common shares at $2.0928 per share under the 2023 agreement or $5.0478 under the 2024 agreement, or at the IPO price if that price is lower. This means the notes’ value rises as Anthropic’s value rises. The filing says Anthropic’s accumulated deficit “includes $113.2 billion related to changes in the fair value of our convertible notes”.
What Happens at the IPO
The S-1’s example figures assume that the outstanding convertible notes will turn into Class N common shares just before the IPO is completed. The conversion is limited to the amount that keeps Amazon Web Services below its ownership limit. The filing leaves the dollar amount blank.
The filing says any amount above the ownership limit “will automatically convert, subject to Amazon’s ownership cap, into shares of our Class N common stock at the applicable conversion price at the end of each fiscal quarter following this offering”. If some notes still have not converted by their maturity date, “such balance will be repaid in cash at such maturity date.” The filing also says Amazon “may” waive the ownership limit at its own choice.
The Chart’s Other Numbers
Sikand Media’s chart adds about $70 billion in estimated net IPO proceeds to the $131.7 billion. A note under the chart says this assumes a “reported ~$75B target, less fees, RSU tax withholding and any shares sold by existing holders”. The S-1 does not state the proceeds amount. The Wall Street Journal reported, citing sources, that Anthropic could raise about $100 billion at a valuation between $1.5 trillion and $2 trillion.
For Alphabet, the chart shows about $144 billion, based on “$242B cash but $98B debt.” Alphabet’s 10-Q for the three months ending 30 June 2026 reports $242.47 billion in cash, cash equivalents and short-term investments. It also reports $98.17 billion in long-term debt due after one year and $2.00 billion in current long-term debt. Subtracting both debt figures leaves $142.3 billion, based on our calculations. We did not check the chart’s figures of about $380 billion for Berkshire Hathaway or about $66 billion for NVIDIA.
Two Readings on X
Jukan, who posts as @jukan05, wrote on 27 October: “Anthropic has more cash and cash equivalents than Amazon… I don’t understand why people keep spreading fearmongering FUD about Anthropic going bankrupt.” Dawson Lee, who posts as Li Daosen, quoted the post and argued the opposite. He said the $132 billion “was raised via $140B in external preferred equity, SAFEs, and convertible debt” and “The cash is legally ear-marked to fund these commitments.”
Lee wrote that the S-1 shows “over $230B in multi-year, non-cancellable compute obligations ($110B locked to Amazon AWS and $120.5B to SpaceX)”. The S-1 says Anthropic agreed to spend “at least $110.0 billion between May 2026 and April 2036, regardless of actual usage” with Amazon. This agreement cannot be cancelled unless Amazon commits a serious breach and does not fix it. The SpaceX figure is “up to $120.5 billion”. The filing says that after the first non-cancellable periods end in January and March 2027, “each agreement may be cancelled by either party upon 90 days’ advance written notice”.
Lee also said Anthropic’s “operating cash flow is deeply negative.” But the S-1’s cash flow statement shows that Anthropic used $1,627 million in operating cash in 2023, $5,692 million in 2024 and $2,637 million in 2025. In the first half of 2026, it generated $3,929 million in net cash from operating activities. We reported that half-year figure, minus spending on long-term assets, in an update to our article about Anthropic’s $80.7B loss becomes a $2.7B adjusted profit. We did not check Lee’s claim that Anthropic had raised $140 billion in capital.
The Risk Factor Bloomberg Flagged
Bloomberg reported that Anthropic “warned it may need to seek more financing sooner than the artificial-intelligence company had anticipated”. The S-1 says its cash and cash equivalents, money earned from sales and available credit should be enough “for at least the next 12 months from the date of this prospectus”. It then warns: “As a result of these and other factors, we may be required to seek additional financing sooner than we currently anticipate.”
The filing adds: “Even if we determine that additional financing is required, we may not be able to raise it on terms acceptable to us or at all. Any such financing, if completed, may be costly, dilutive, or lead to restrictions on how we operate our business.” In other words, Anthropic may not be able to raise more money when needed, or may have to accept expensive terms, give up a larger share of the company or agree to limits on its business.
Connecting the Coverage
On 26 October, we reported that the same Anthropic notes are $108.6B in debt for Anthropic and a $97.9B asset for Amazon. We also reported that Anthropic earned $762M in interest in Q2 on its $131.7 billion in cash. Today, we reported that Anthropic’s computing leases that had not yet started reached $321.4 billion on 30 June. These obligations are not included in either net-cash figure.
The Structural Read
In our reading, the $108.6 billion figure measures what the notes are worth to Amazon based on Anthropic’s valuation. It is not the amount of cash Anthropic owes. The S-1 says the notes turn into Class N shares at the IPO. Any amount that has not converted by maturity must be repaid in cash. The filing also allows cash repayment in certain liquidation events or if certain defaults occur.
In our reading, the two posts on X answer different questions. Jukan compares the companies’ cash balances, while Dawson Lee compares Anthropic’s cash with its contracts. The S-1 says the Amazon agreement cannot be cancelled, while the SpaceX agreements can be cancelled with 90 days’ notice after their initial periods end in early 2027.
In our reading, the S-1’s own cash flow statement shows that the first half of 2026 was the first period in the filing when Anthropic generated net cash from operating activities, following three full years when it used cash for operations.
Anthropic, PBC, Form S-1, management discussion and analysis, filed 26 October 2026
“we may be required to seek additional financing sooner than we currently anticipate”
Three Implications
FOR INVESTORS COMPARING CASH PILES The S-1 leaves blank both the amount of notes that will convert at the IPO and the amount of money the offering will raise. So any estimate of net cash after the IPO, including Sikand Media’s estimate of about $200 billion, depends on assumptions that are not stated in the filing.
FOR AMAZON The S-1 says Amazon’s notes convert into Class N shares at the IPO up to its ownership limit. Amazon may choose to waive that limit. Any remaining notes convert every three months after the offering.
FOR COMPUTE SUPPLIERS The S-1 says Anthropic must spend $110.0 billion with Amazon regardless of how much computing it uses. Its SpaceX contracts can be cancelled with 90 days’ notice after their initial periods end in early 2027.
The Business Engineer Lens
This story connects to the Business Engineer framework The AI Capex Map and the State of AI.
The framework says that “cloud providers now hold roughly $2.1 trillion in revenue backlog, and half of that — $1.05 trillion — comes from two cash-burning AI startups, OpenAI and Anthropic.”
In our reading, the S-1 shows the other side of those future payments: Anthropic has promised to spend $110.0 billion with Amazon regardless of how much computing it uses, while holding $131.7 billion in cash. The framework was published before this filing and does not discuss it.
What Is Not Established
The S-1 does not state how much of the $6.2 billion in principal will convert at the IPO or how much money the offering will raise. So the filing alone does not provide enough information to calculate net cash after the IPO. The chart’s ranking also relies on figures for Berkshire Hathaway and NVIDIA that we have not checked.
The Bottom Line
Anthropic had $131.7 billion in cash and short-term investments. After subtracting the $108.6 billion fair value of Amazon’s convertible notes, it had $23.1 billion in net cash, based on our calculations from the S-1. If the notes convert into shares at the IPO, the net-cash figure would remain close to $131.7 billion, based on our calculations. The notes have $6.2 billion in principal.
A note on sources. The Anthropic figures come from Anthropic, PBC’s Form S-1, filed with the SEC on 26 October 2026 and read on EDGAR on 27 October 2026. The relevant sections are the balance sheet, Note 9, the prospectus summary and the sections on liquidity. Alphabet’s figures come from its Form 10-Q for the quarter ending 30 June 2026. We calculated the net figures ourselves. Sikand Media’s chart was shared with us on 27 October. Its figures for Berkshire Hathaway and NVIDIA and its estimate of IPO proceeds came from Sikand Media and were not checked by us.
Bloomberg’s and the Wall Street Journal’s reports are presented as published. This is not investment advice. We did not contact Anthropic or Sikand Media.
Sources: Anthropic, PBC Form S-1, filed 26 Oct 2026 (SEC EDGAR): balance sheet, Note 9, prospectus summary, liquidity and risk factors · Sikand Media chart, posted on X by Michael Sikand, 26 Oct 2026 · Alphabet Inc. Form 10-Q for the quarter ending 30 June 2026 (SEC EDGAR) · Bloomberg on X, 27 Oct 2026 · Dawson Lee (Li Daosen) on X, 27 Oct 2026, quoting Jukan